The offers on my desk
right now.
These are the new-car offers I currently have access to, written out plainly - every figure, every condition, nothing in the small print that is not also up here in the large print.
Offers come and go as allocations change, so if something here fits, tell me and I will confirm availability the same day. Last updated June 2026.
BMW 1 Series M Sport
First year's insurance included, three years' servicing included, 6,000 miles per annum over 48 months. Just one month's rental up front.
BMW 1 Series M Sport
6,000 miles per annum over 48 months. This offer does not include a service plan or insurance.
BMW 2 Series Gran Coupé
48 months, 6,000 miles per annum. Ask me for the full written quotation and specification.
Recently gone: the X1 xDrive25e M Sport and the iX3 50 xDrive M Sport Pro have both found homes. If either was the one you wanted, leave your details on the X1 page or the iX3 page and I will let you know when the next arrives.
Prices shown exclude our BMW Protection Package. Ask me about adding this to your quotation and I can provide a combined figure.
Finance subject to status. Available to UK residents aged 18 and over. Stephen James (Automotive) Ltd, trading as Hedin Automotive (BMW Ruxley), is an Appointed Representative of ITC Compliance Limited, which is authorised and regulated by the Financial Conduct Authority (Firm Reference No. 313486). Hedin Automotive (FRN 738497) is a credit broker, not a lender. BMW Financial Services (GB) Limited (FCA No. 312705) is the lender. All offers shown are Personal Contract Hire (PCH), not consumer credit; no APR applies to PCH agreements. You do not own the vehicle and there is no option to purchase at the end of a PCH agreement. BMW 1 Series representative example: BMW 120 M Sport. Initial rental £389, 47 monthly rentals of £389, total amount payable £18,672, 48 month term, 6,000 miles per annum. Road fund licence included. BMW 1 Series representative example (no service plan or insurance): BMW 120 M Sport. Initial rental £500, 47 monthly rentals of £320, total amount payable £15,540, 48 month term, 6,000 miles per annum. This offer does not include a service plan or insurance. BMW 2 Series Gran Coupé representative example: initial rental £399, 47 monthly rentals of £399, total amount payable £19,152, 48 month term, 6,000 miles per annum. Excess mileage charges apply on all agreements. Prices and availability correct at date of publication and may be withdrawn or changed without notice. Written quotations available on request.
Protection, honestly framed.
These are the official Hedin Automotive protection products available on your BMW. I will explain what each one actually covers - and, just as honestly, when you do not need it. Tell me how you use the car and I will tell you which of these genuinely earn their keep for you, and which to skip. Links go to Hedin's own product pages.
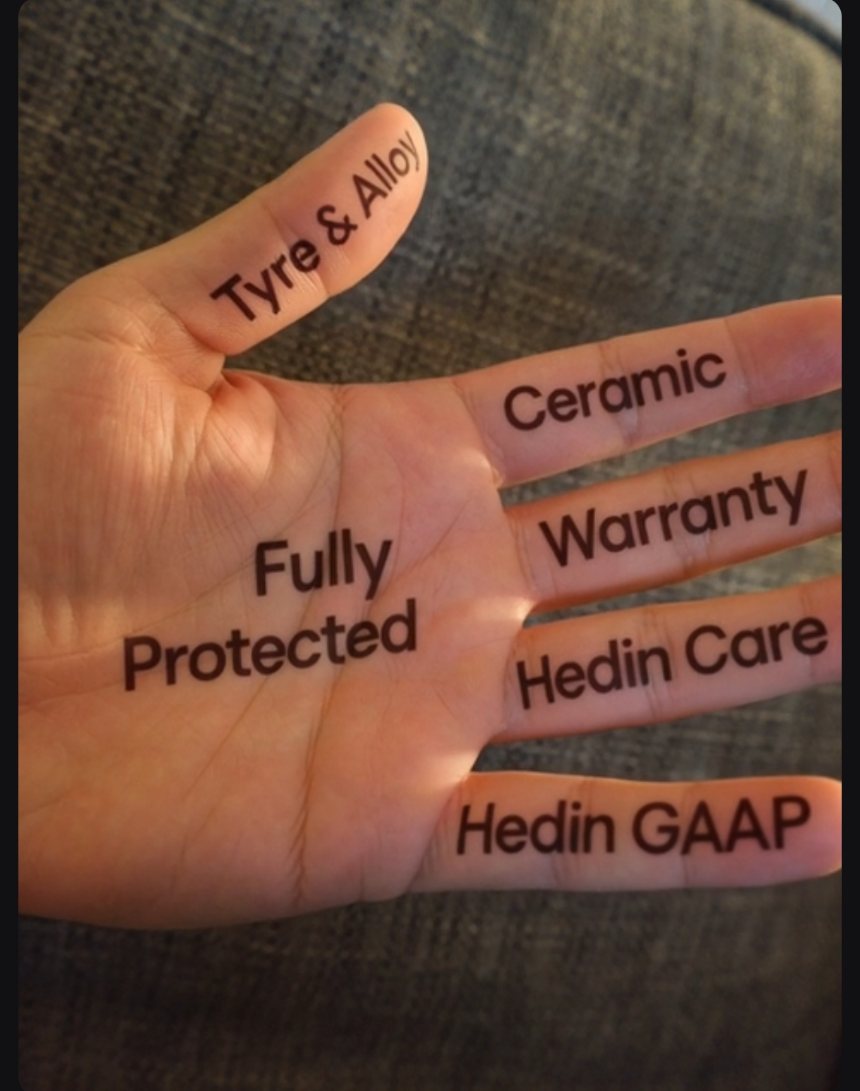
Hedin’s Fully Protected Package comprises of 5 elements. One per finger, and I will go through them exactly like this in person. Tap any one below to see what it covers, what it will not, and whether I think it earns its keep on your car.
Cosmetic repair - Club HedinCare
Chips up to 1.5cm and dents up to 30cm across and 3mm deep, repaired as often as you need, without ever touching your insurance.
What counts as a SMART repair
- Stone chips up to 1.5cm
- Minor dents up to 30cm across and 3mm deep
- Light scratches and scuffs - the car park, the gatepost, the trolley
- Unlimited repairs for as long as the membership runs, so the size limit is the only real limit
How it works
- 24 or 36 month terms
- Repairs are never reported to your motor insurer, so your no claims bonus is untouched and your premium does not move
- Within 10 miles of a Hedin dealership our own technicians do it; further out, a mobile repair unit comes to you at a time you pick
- Twice-yearly assessments, plus interim visits at reduced rates
- Book through the member portal or on 0344 573 8187, Monday to Friday 9am to 5pm and Saturday 9am to midday
- Administered by Car Care Plan Limited
Where the size limits bite
- A dent deeper than 3mm, or wider than 30cm, is a bodyshop job and falls outside it. So does anything that has cracked or broken the paint badly enough to need a panel
- Damage already on the car when the policy starts is not covered - this protects the condition it is in, it does not put right what is already there
My honest take. This is the one most people actually use. If you park in town, use multi-storeys, or have kids and car seats, the dings arrive whether you are careful or not - and three of them at bodyshop prices costs more than the policy.
Skip it if the car lives in a garage, does low miles, and a light scuff genuinely would not bother you. And be realistic about the 30cm and 3mm: it is built for supermarket dings, not for a proper knock.
Tyre & alloy wheel cover
Fifteen tyre replacements and fifteen alloy repairs across a three year term, plus unlimited puncture repairs, for kerbed rims and split sidewalls.
What it pays
- Fifteen tyre replacements over the policy term, up to £150 each and £2,250 in total
- Fifteen alloy wheel repairs, up to £150 each including VAT, and £2,250 in total
- Unlimited puncture repairs, up to £50 each, including a new valve, rebalancing and disposal
- A contribution of up to £150 towards a replacement wheel if one is damaged beyond repair - that counts as one of your fifteen
- Unlimited repair or replacement of alloy inserts, the fins and blades, up to £250 each
- The term runs to a maximum of 36 months
The conditions that catch people out
- Damage must be reported within 30 days of it happening
- Tread must have been legal at the time - a bald tyre that then gets damaged is not covered
- Wear and tear is not covered, and neither is a wheel already showing rust or corrosion
- Not for accidents, fire, theft or flood - those belong to your motor insurance
- Malicious damage needs a crime reference number
- The policy has to be bought within 30 days of the car
- Chrome, polished and split-rim wheels are excluded - the repair process cannot restore those finishes
- Excluded if the car is used for business or commercial hire, dispatch, hire and reward, driving instruction, chauffeuring, track days or competition
- Cover runs in the UK, Ireland, the Isle of Man and the Channel Islands, plus up to 60 days per trip in Switzerland and the EEA
- The policy cannot be renewed at the end of the term
- Cancel within 30 days for a full refund; after that it is pro-rata, less a £35 admin fee
My honest take. This is about wheel size and where you drive, not about how careful you are. A 20 inch M Sport rim and a low profile run-flat is a serious bill for one bad kerb, and London kerbs win every time.
On 17 or 18 inch wheels with a normal tyre, out of town, it is a much harder case to make. Note the £150 per claim ceiling: on a big diamond-cut wheel that is a contribution, not the whole job.
Asset protection - GAP
Covers the gap between your insurer's payout and what you actually paid, or still owe, if the car is written off or stolen.
What it pays on a total loss
- The greater of: the difference between the insurer's valuation and what you paid, the difference between the valuation and your finance settlement, or the premium you paid for the policy
- Capped at the purchase price of the car, up to £50,000
- Your motor insurance excess up to £500, where you cannot recover it from a third party
- A contribution towards a hire car - up to 30 days at £30 a day
- Separately, £500 a year towards your excess on ordinary claims that are not a write-off
- Purchase price includes factory options and dealer-fitted accessories up to £1,500, but not any discount you negotiated
- Available over 36 or 48 months
What it will not pay
- Negative equity carried over from a previous car, or finance arrears
- Road fund licence, number plates, admin fees, fuel, or paint and upholstery protection kits
- VAT, if you are VAT registered and can reclaim it
- Anything where your insurer offered to repair the car and you pushed for a write-off instead
- The shortfall, if your insurer provides a replacement vehicle under your own policy
My honest take. This matters most in the first two or three years of a nearly new car, and most of all on finance - that is exactly when the gap between what a car is worth and what you owe is at its widest.
If you paid cash for something four or five years old, depreciation has already happened and the gap is small. Check your own motor policy first, too: some already include new-for-old in year one, which does part of this job.
Extended warranty
Another 12, 24 or 36 months on top of the manufacturer cover, with wear and tear, breakdown assistance and MOT test cover included.
What is covered
- Adds 12, 24 or 36 months - you choose the extension, and the longest takes total cover to at least four years
- Unlimited claims, up to the value of the car when you bought it in total
- Parts and labour in full, using new manufacturer-specification parts, with nothing to pay towards them
- Wear and tear included, which is the thing most warranties quietly leave out
- Engine, gearbox, clutch, turbo, ECU, electrics, air conditioning, ABS, airbags, suspension, steering, DPF, catalytic converter, sat nav and infotainment, LED lighting, wheel bearings
- A mid-sized saloon for up to seven days while yours is in, after the first 24 hours
- Up to £60 towards a hotel or train fare, and up to 60 days a year of cover in the EU and EFTA
- Transferable for £25 if you sell the car privately - a genuine selling point at that stage
MOT test cover
- Up to £750 per MOT towards putting right anything on the failure sheet
- Lamps and reflectors, steering, suspension, brakes including ESC and the electronic parking brake, seat belts and airbags, structural corrosion, TPMS, wipers, and emissions parts like the EGR valve, catalytic converter and DPF sensor
If it is a hybrid or an EV
- The traction battery pack, electric motor, onboard charger, DC to DC converter, power electronics, thermal cooling, charge port, electric transmission and generator are all covered
- Run out of charge and they will recover you and up to five passengers to the nearest charge point, home, or your destination - twice per warranty year
Breakdown assistance
- 24 hours a day, covering the car rather than the driver, so whoever is behind the wheel is covered
- Roadside and recovery for the car plus five passengers, home start, accident assistance and puncture cover, across Great Britain, Northern Ireland, the Channel Islands and the Isle of Man
My honest take. The wear and tear cover is what separates this from a cheap third-party warranty, and the MOT cover quietly pays for itself on an older car. If you are keeping the car past the manufacturer warranty, this is the one I would not skip.
On a used EV it is worth more than people realise: the traction battery is most of the car's value, and it is covered here. Match the term to how long you are actually keeping it - there is no sense buying thirty six months on a car that is going in two years, which is exactly why the twelve and twenty four month options exist.
Ceramic paint protection - Williams Racing
A ceramic coat on the paint and a protective film through the interior fabric, applied before you take the car, with a lifetime guarantee.
Two parts to it
- Ceramic coat bonds into the pores of the paint rather than sitting on top of it, leaving a high gloss finish and a surface that sheds tree sap, pollutants and everyday weather
- Interior protection coats each fibre with a film, so spillages sit on the surface long enough to lift off instead of soaking into the seat
- Carries a lifetime guarantee
- Applied before handover, so the car arrives already done
What it is not
- It is not a substitute for the cosmetic repair cover above. Ceramic protects the finish; it does not undo a stone chip or a dent
- It makes the car easier to keep clean rather than impossible to mark
My honest take. It earns its keep on solid dark colours, black and Carbon Black especially, where swirl marks from washing show up worst, and on light interiors like Oyster or Canberra Beige that mark easily.
If you detail the car yourself and enjoy it, you can get most of the way there with your own products and a weekend. This is for people who would rather it was already done and want the guarantee behind it.
Cover levels, limits and exclusions summarised here come from Hedin Automotive's own product pages and the policy documents linked from them, and are correct as far as I can tell at the time of writing. They are a summary, not the policy: the terms and conditions and the product information document decide what is covered in any given case, and I will give you those before you buy anything. These are insurance products. Hedin Automotive London Ltd & Stephen James (Automotive) Limited are an appointed representative of ITC Compliance Limited which is authorised and regulated by the Financial Conduct Authority (their registration number is 313486). Permitted activities include advising on and arranging general insurance contracts and acting as a credit broker not a lender.